How to Buy a Home in Thornton: A Clear Step-by-Step Guide
March 24, 2026
March 24, 2026
Buying a home in Thornton should feel exciting, not overwhelming. If you want a clear path from first search to keys in hand, you’re in the right place. In this guide, you’ll learn each step of the process, Thornton-specific tips that save time and stress, and simple checklists you can use right away. Let’s dive in.
Recent reports show Thornton prices in the mid 400s to low 500s, with more listings and slightly longer days on market than the peak years. That gives you a bit more room to compare homes and negotiate. Keep in mind that results vary by neighborhood and price band.
Thornton sits just north of Denver with quick access to I‑25 and E‑470. You’ll find a mix of established neighborhoods and large new master-planned communities on the north side. Many buyers weigh commute time, proximity to parks, and attendance boundaries for Adams 12 Five Star Schools. Always verify school assignments directly with the district.
Start by gathering your financial documents and securing a written pre-approval. This tells sellers you are serious and shows your price range, loan type, and estimated monthly payment.
Lender checklist:
Common loan types in Thornton include conventional, FHA, VA, and sometimes USDA for eligible areas. Ask lenders about typical underwriting times for Colorado loans. Many standard loans close in 30 to 45 days once you are under contract, depending on the lender’s workflow.
If you need help with your down payment or closing costs, explore the statewide options from the Colorado Housing and Finance Authority. You can review current programs on the CHFA homeownership pages. For details, visit the CHFA overview of down payment assistance on the CHFA homeownership site.
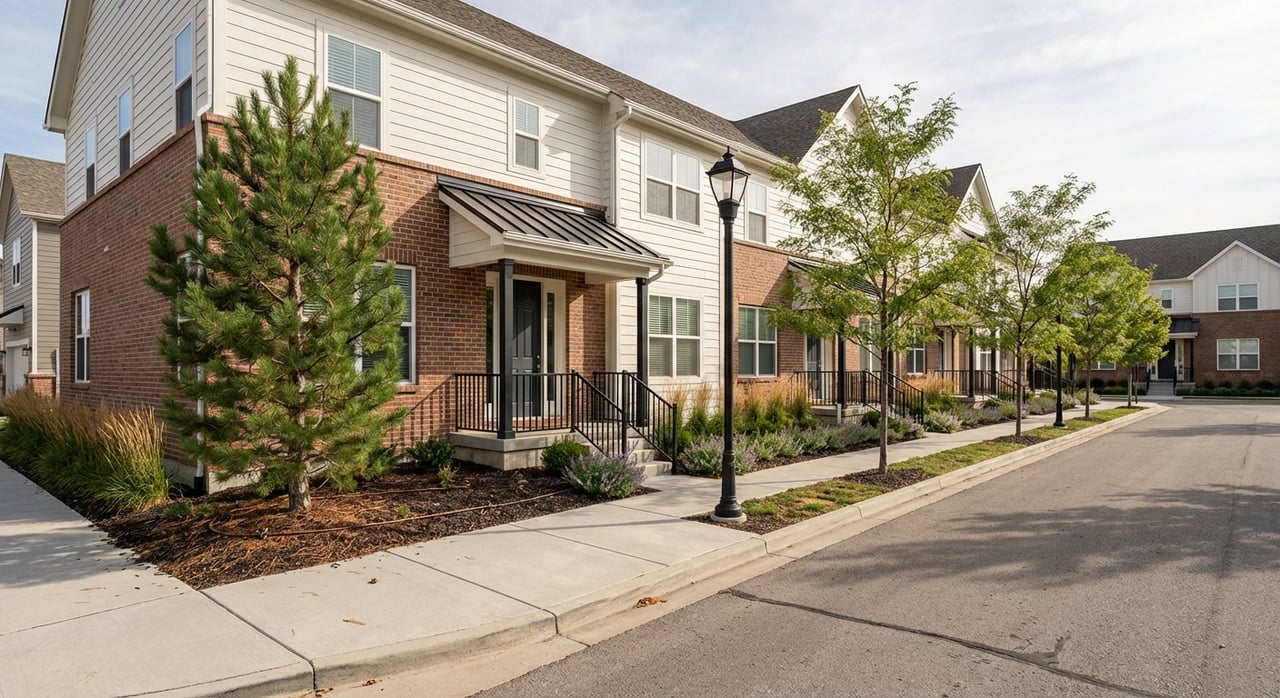
Decide how you want to live, then pick areas that fit. Thornton offers single-family homes, paired homes, and townhomes across many ages and price points. North Thornton also features major new master-planned communities like Parterre with national builders.
Neighborhood-fit checklist:
New builds follow a different process than resale. Builder contracts are not the standard Colorado forms. Ask for the builder’s contract, selection schedule, deposit requirements, and written warranty coverage before you commit.
A clean, confident offer includes your pre-approval letter, earnest money, and clear deadlines. In many Colorado purchases buyers offer around 1 percent of the price for earnest money in ordinary markets. In more competitive situations, you might see larger deposits.
Colorado uses the Colorado Real Estate Commission contract with built-in deadlines for inspection, appraisal, and loan approval. Inspection deadlines often land about 7 to 14 days after acceptance, and financing deadlines commonly range from 21 to 30 days. All timing is negotiable and must match the written contract. To see the official state contract forms and timelines, visit the Colorado Division of Real Estate contracts and forms.
Order your general home inspection right away. Then add targeted tests that are smart for the Front Range. Radon testing is common, and Colorado law now requires sellers to disclose known radon information. Even with disclosure, you should still test for your own peace of mind because results can change over time. You can review the current radon law on the Colorado Legislature’s SB23‑206 page.
Other frequent local findings include roof wear from hail, grading and drainage issues near foundations, and older HVAC or water heaters nearing end of life. A sewer-scope inspection is wise for older homes or those with mature trees. Typical timelines: many inspectors deliver reports within 2 to 4 days, and inspection objection windows are often set at 7 to 10 days, based on your contract.
Common cost notes to keep in mind:
Inspection add-on checklist:
Your lender orders the appraisal to confirm the value supports the price. Scheduling and reports can take a few days to as long as 2 to 3 weeks, depending on appraiser availability. While the appraisal is in progress, your lender works on title, verification, and final approval. Once all items are cleared, you will receive the clear-to-close.
Plan for a final walk-through 24 to 72 hours before closing to confirm the home’s condition and any agreed repairs. In Colorado, title companies typically handle closings. You will sign loan and title documents, funds are exchanged, and you receive your keys.
A typical contract-to-close timeline is 30 to 60 days for standard mortgage loans. Buyers usually pay loan-related fees, appraisal, and their share of title and escrow costs. Closing costs often total about 2 to 5 percent of the purchase price, depending on the loan and property. Ask your lender for a Loan Estimate up front and a Closing Disclosure before settlement so you can review every line item.
Right after closing, transfer utilities and set up services. The City provides water and sewer service information through Thornton Water. If your home is part of an HOA or metro district, complete onboarding and set payment preferences.
If you bought new construction or a recently built home, ask the builder to confirm any outstanding warranty items and how to file claims. For property taxes, Colorado taxes are based on assessed value and include county and local district mill levies. You can look up the parcel and mill levy details through the Adams County Assessor.
Parterre and other north Thornton projects bring many new-home choices. New builds may offer incentives and modern systems, but you should confirm whether any utility connection or impact fees were factored into the price. Ask which party pays remaining connection or plant investment fees. Thornton Water posts current rate and fee schedules on the Thornton Water site, which can help you ask the right questions.
Before signing, review the builder contract and warranty. Clarify what is included, how deposits and escrow are handled, timelines for selections, and the process for punch-list items at closing. Because builder agreements differ from the standard Colorado contract, make sure you understand deadlines and cancellation rights before you commit.
Your minimum down payment depends on your loan program. If you are a first-time buyer or meet income limits, you may qualify for down payment assistance. CHFA offers statewide options that pair with common loan types and provide grants or second-mortgage assistance, based on program rules. Explore current eligibility and program amounts on the CHFA homeownership site.
Thornton also participates in Adams County partnerships that coordinate housing support. Program details change with funding cycles, so confirm the latest options with the city, county, or your lender.
If you want a calm, step-by-step plan and a dedicated advocate focused on Thornton and the north suburbs, let’s talk. Schedule your Free Buyer Consultation with Tara Sisneros and get a custom game plan for your budget, timeline, and must-haves.
Stay up to date on the latest real estate trends.
I am committed to guiding you every step of the way—whether you're buying a home, selling a property, or securing a mortgage. Whatever your needs, I've got you covered.
Tara Sisneros
11859 Pecos St Ste 200 Westminster CO 80234